
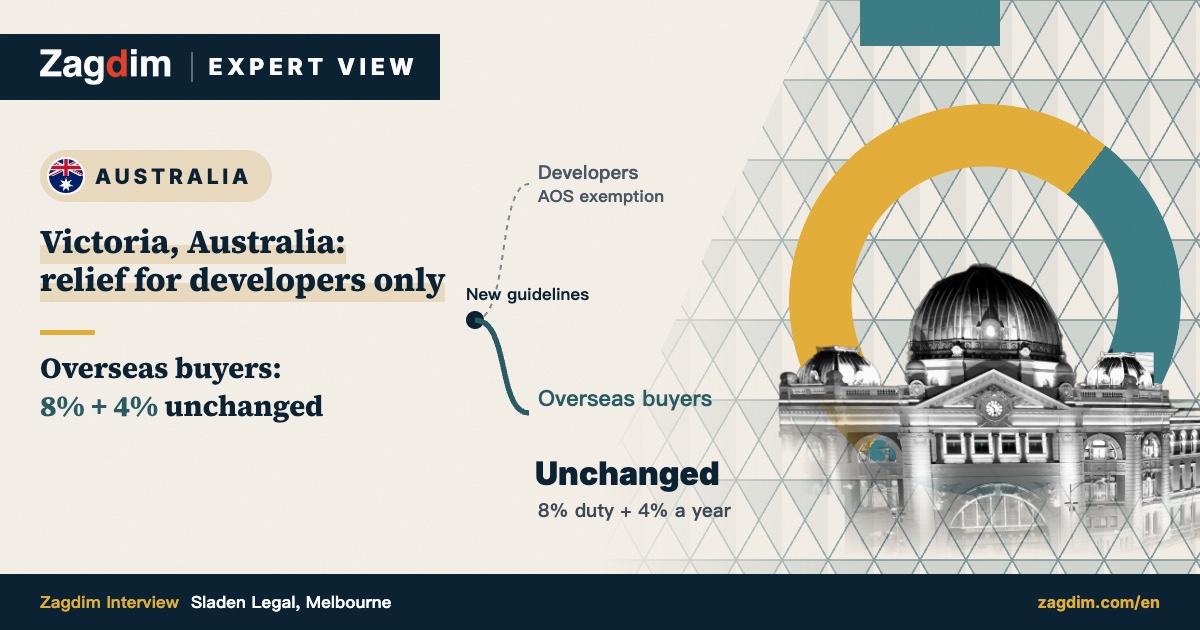
On 27 October 2026, the Victoria Government Gazette published new guidelines signed by Treasurer Colin Brooks on exemptions from the Absentee Owner Surcharge (AOS), the land tax surcharge on land held by absentee owners. The new guidelines replace the 2018 version. The headline change: an eligible company or trust whose business is mainly residential development can now have its exemption cover both the construction phase and two years after completion.
The state government announced the change on 14 October, saying only that it would update the guidelines. Two weeks later the guidelines are out. For overseas families thinking about buying in Melbourne, the questions are simple: does this affect me, and has the 8% Foreign Purchaser Additional Duty (FPAD) on purchases changed? Zagdim asked Nicholas Clifton, Principal Lawyer at Sladen Legal in Melbourne, how it looks in practice.
In short: the new guidelines deal only with the AOS under land tax, and they apply to Australian-incorporated development companies and trusts with foreign shareholders or beneficiaries, not to individual buyers. The 8% FPAD on purchases is unchanged, and individual absentee owners still pay the 4% AOS each year. The government has also said it would review both surcharges if re-elected, but that depends on the state election on 28 November. If you are planning to buy in Victoria, keep both costs in your budget and check your buyer status and ownership structure before you sign.
Two Surcharges: One at Purchase, One Every Year
A foreign buyer of residential property in Victoria will usually face two extra costs. They work differently, and only one of them has been touched.
| Item | When it is paid | Rate | Changed this time? |
|---|---|---|---|
| Foreign Purchaser Additional Duty (FPAD) | Once, on purchase of residential property | 8% (agreements entered into on or after 1 July 2019) | No |
| Absentee Owner Surcharge (AOS) | Every year, with land tax, while you own the land | 4% (from the 2024 land tax year; 2% in 2020–2023) | Only the exemption criteria for companies and trusts; individual owners are unaffected |
According to the State Revenue Office (SRO), the AOS is assessed on your status at 31 December: if you are an absentee owner on that date, the surcharge applies in the following land tax year. It does not apply if the total taxable value of your land is below $50,000 ($25,000 for land held on trust where the trust rate applies). Australian citizens and permanent residents who live overseas are not absentee owners; from 1 January 2026, New Zealand citizens are subject to the same rules as other foreign citizens.
On FPAD, the SRO notes that when a foreign purchaser is nominated to take a transfer of residential property under an off-the-plan contract, FPAD applies.
What the New Guidelines Change
The guidelines set out who can be granted an exemption. They do not lower the rate. Under the Land Tax Act 2005, a corporation in which an absentee person holds a controlling interest, or a trust with absentee beneficiaries, is generally liable for the AOS. The Treasurer may exempt those absentee persons from being treated as holding that interest, so that the corporation or trust no longer pays the surcharge. The guidelines state that this will not exempt a corporation incorporated outside Australia, and that all other land taxes remain payable.
The starting point is that an entity seeking the exemption should be Australian-based, make a significant contribution to the Victorian economy and community, and show good corporate behaviour, including compliance with Foreign Investment Review Board requirements and Victoria’s tax laws. The exemption is not intended for an entity that is essentially a landlord or passive investor.
Two additions stand out:
| New content | What the guidelines say (summary) |
|---|---|
| Examples of “significant contribution” | Developments that may be considered to contribute significantly while development activities are under way include a build-to-rent development, and projects that meet the Significant Residential Developments with Affordable Housing criteria under the Development Facilitation Program (DFP) |
| Two years after completion for residential development | Where an exemption is granted to an entity engaged in residential property development in Victoria, with predominantly residential developments, it covers the active development phase and a two-year period after completion |
The DFP criteria differ by location:
| Location | Development cost | Affordable housing | If the application includes rezoning, also required |
|---|---|---|---|
| Metropolitan Melbourne | $50 million | At least 10% of total dwellings | Support from state, regional and local policy; civil infrastructure and services readily achievable and supported by servicing agencies |
| Regional Victoria | $15 million | At least 10% of total dwellings | Less than five years of residential supply in the locality; land within a defined settlement boundary and supported by state, regional and local policy; civil infrastructure and services readily achievable and supported by servicing agencies |
The guidelines also keep a general rule: a development may be treated as contributing for one year after completion, to allow for the sale of the developed land. If the development is built for lease, that extra year will generally not apply, because once construction is complete the owner is treated as a passive investor, essentially a landlord. Residential development has the separate two-year rule above.
Nicholas Clifton points out that only land tax has been updated:
“Just land tax only (no update to the Duties guidelines).”
In other words, nothing has changed for the 8% FPAD that foreign buyers pay on residential purchases.
What Is in Force, and What Depends on the Election?
The new guidelines replaced the 2018 version on the day they were gazetted. Everything else is still a policy promise.
| Status | Details |
|---|---|
| In force | New AOS exemption guidelines, signed by the Treasurer on 23 October 2026 and gazetted on 27 October 2026; the guidelines of 1 October 2018 are revoked from the date of gazettal |
| Unchanged | FPAD at 8%; AOS at 4% for individual absentee owners; AOS exemptions still require an application and are assessed case by case |
| Not yet clear | The guidelines do not say how they apply to developments already under way or to past land tax years |
| Depends on the election | According to Australian media reports, the Labor government has committed to reviewing the AOS and FPAD if it wins the state election on 28 November; no scope or timetable has been published |
Under the Victorian Government’s caretaker guidelines, the caretaker period began at 6:00pm on 3 November 2026; during this period the government generally avoids implementing major policy decisions. The new guidelines were gazetted before it began.
Before the guidelines were published, Nicholas Clifton noted a gap in the October announcement: “The government’s announcement was not clear whether the absentee owner surcharge (ie foreign owner land tax surcharge) rules will be changed for existing developments or only new developments.” After the guidelines were published, he added: “It may be possible for existing developments under construction to apply for the exemption (subject to approval by the Treasurer) – but this is not clear.” The published guidelines do not spell this out either.
Individual Overseas Buyers: What Should You Expect?
For individual buyers, the numbers stay the same. Nicholas Clifton’s advice is direct:
“As there is no change to the stamp duty guidelines, buyers should still be prepared to pay the 8% foreign purchaser additional duty. Eligible companies and trusts can apply for the exemption under the new Treasurer’s guidelines – but individuals and other entities cannot obtain any relief (even if they would otherwise qualify).”
The same goes for land tax. Under the new guidelines published in the Government Gazette on 27 October, the exemption is open to companies and trusts, not to individuals; according to the SRO, individual absentee owners still pay the 4% AOS each year.
Where buyers get caught out is their status and ownership structure around the time of signing. Nicholas Clifton highlights three situations:
1. The window between contract and settlement. “In Victoria, it is possible to sign a contract and then ensure that the purchaser is not treated as a foreign or absentee owner before settlement. In most other States, however, the additional stamp duty liability can apply from the contract date.”
The rules differ from state to state. What works in Victoria may not work elsewhere, so check before signing when and in what capacity you will be assessed.
2. Buying through a discretionary trust. “If property is purchased in a discretionary trust, appropriate foreign person exclusion clauses will be required to ensure that the trust is not treated as foreign. These may not be possible to include, however, where there are foreign persons behind the purchase.”
3. Nominating a new buyer after signing. “Nominating a new buyer after contracting to purchase a property can result in double stamp duty in Victoria, if there has been any land development (which includes preparing a plan of subdivision and making applications for planning permits etc).”
This is consistent with the SRO’s guidance that nominating a foreign purchaser under an off-the-plan contract is a sub-sale event, because land development has occurred, and FPAD applies.
All three situations arise around the time of signing, which is why checking early leaves more options. Here is what to confirm before you sign:
| What to check | Why it matters |
|---|---|
| Your status (and any co-buyer’s) at settlement and at each 31 December afterwards | FPAD and AOS both depend on whether the buyer is foreign or absentee; AOS is assessed every 31 December |
| Whether you buy as an individual, a company or a trust | A trust needs appropriate foreign person exclusion clauses, which may not always be possible |
| Whether the contract allows, or you may need, a nomination | Nominating a new buyer after land development can mean paying duty twice |
| Your annual holding cost | Absentee owners pay the 4% AOS on top of ordinary land tax |
Table: based on Nicholas Clifton’s comments and published SRO guidance (October 2026)
Developers: How the Relief Works
The exemption is not automatic. It requires an application and an assessment. The DFP criteria and build-to-rent are listed as examples of developments that may be considered to make a significant contribution. Whether an exemption is granted still depends on factors such as the degree of foreign ownership and control, whether there is management staff based in Australia, the entity’s actual contribution to Victoria and its tax record.
The extra conditions in the rezoning column of the DFP table above (policy support, civil infrastructure and services, residential supply) do not apply to every project. As Nicholas Clifton explains: “These are typically required to be shown based on the wording in the guidelines where there is a rezoning component. If there is no rezoning required, then this will not be necessary.”
Nicholas Clifton adds that meeting the DFP criteria has value beyond tax: the DFP expedited planning pathway “will still give benefits in expediting the planning permit application process and potentially maximise the development possible on a lot.”
The Bottom Line
The new guidelines ease the AOS for residential developers during construction and for two years after completion. For individual overseas buyers, the 8% FPAD and the annual 4% AOS are unchanged. Whether anything further follows depends on the result of the 28 November election and what the next government does. For families planning to buy in Melbourne, the most practical step now is to budget for both surcharges and check your buyer status and ownership structure before you sign.
If you are considering property in Victoria and are not sure how your status or ownership structure will be treated, tell the Zagdim reader desk about your situation. The reader desk will understand your needs and identify suitable professionals.
Life abroad? Ask Zagdim.
Your first stop for international property and global living.
Research and insights. Know what’s changing. Understand what matters.
Key Terms
- Absentee Owner Surcharge (AOS): a Victorian land tax surcharge, currently 4%, on land held by absentee owners, on top of ordinary land tax.
- Foreign Purchaser Additional Duty (FPAD): an 8% duty that foreign purchasers pay on residential property in Victoria, on top of ordinary stamp duty.
- Treasurer’s guidelines: guidelines issued under the Land Tax Act 2005 and published in the Government Gazette, setting out how AOS exemptions are assessed.
- Development Facilitation Program (DFP): a Victorian program that fast-tracks planning approval for certain developments.
- Build-to-rent: a residential development built to be held and leased long term rather than sold as individual units.
- Caretaker period: the period around a state election during which the government generally avoids major policy decisions.
About This Article
Information was checked on 27 October 2026. Details of the new guidelines are taken from Victoria Government Gazette No. S 643 (27 October 2026); current AOS and FPAD rules are from the SRO website. Labor’s commitment to review the AOS and FPAD if re-elected is based on Australian media reports; it does not appear in the government’s media release of 14 October.
The views quoted in this article are Nicholas Clifton’s practical comments. They are intended as general information rather than advice on any individual case. Quotes were confirmed in writing by Nicholas Clifton. This article is not legal or tax advice; please consult a qualified professional about your own situation.
Experts interviewed
Nicholas Clifton, Principal Lawyer, Sladen Legal
References
Victoria Government Gazette No. S 643, Land Tax Act 2005 Treasurer’s Guidelines (27 October 2026) / Premier of Victoria, “Build Affordable Homes: Pay Less Tax With Labor” (14 October 2026) / State Revenue Office Victoria, Absentee owner surcharge / State Revenue Office Victoria, Absentee corporations / State Revenue Office Victoria, Understanding foreign purchaser additional duty / Victorian Government, 2026 Guidelines on the Caretaker Conventions – FAQ / Elite Agent, “Victoria property tax changes for foreign investors” (15 October 2026)






