This article is for readers who live in the UK and whose family has bank accounts, property or investments outside the UK, and who have received, or are worried about receiving, a letter from HM Revenue & Customs (HMRC) about overseas income.
HMRC writes to people who may not have declared all their foreign income, using financial account data exchanged with other jurisdictions. Its 2024–25 annual report says it sent 20,000 such letters that year. HMRC’s guidance is to check your tax affairs first, and to use the Worldwide Disclosure Facility (WDF) only if you find you need to make a disclosure.
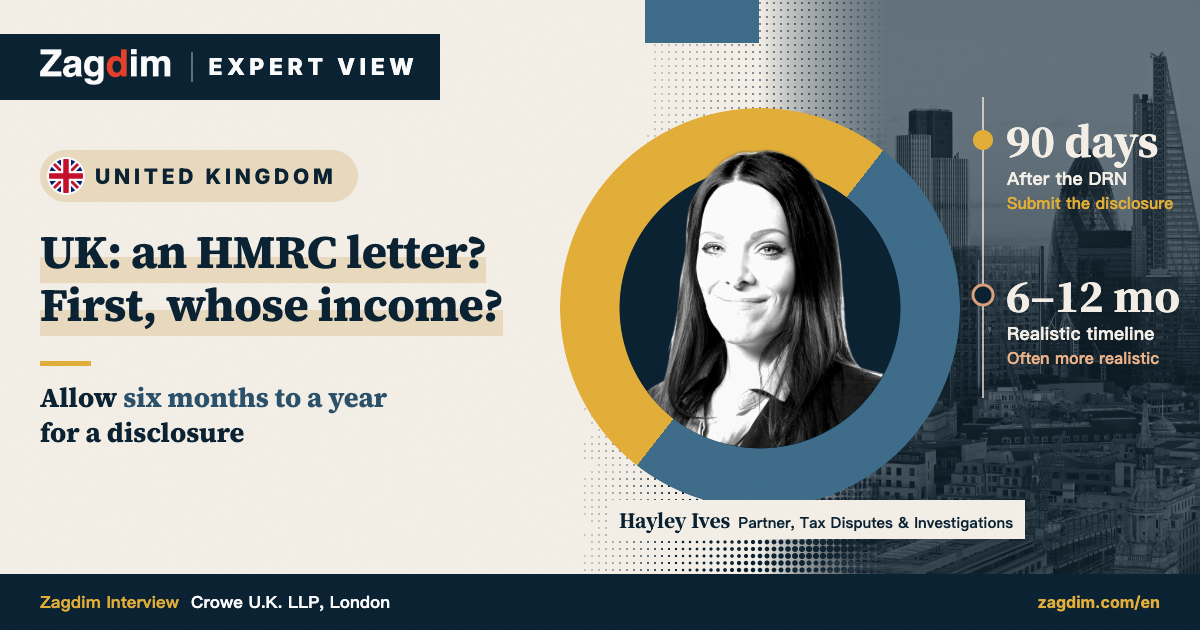
Zagdim interviewed Hayley Ives, Partner, Tax Disputes & Investigations at Crowe U.K. LLP. Her advice: UK tax is assessed on individuals, so the first step is to establish exactly whose income, gains or assets the letter is about; and if a disclosure is needed, six months to a year is often a more realistic timeline.
Key points
- Whose income is it? Hayley Ives notes that UK tax is assessed on individuals, not families. The name on a bank account or property record is not always the person taxable on the income.
- Then compare the records: check HMRC’s concerns against your tax returns and supporting records to see whether there is actually an error to correct, before deciding what to do next.
- Disclosure has two stages: notify HMRC through the Digital Disclosure Service; once a disclosure reference number is issued, in most cases you have 90 days to submit the full disclosure.
- Allow enough time: she says a straightforward disclosure can in theory reach HMRC’s first response in about three to five months, but six months to a year is often more realistic.
- The rules are changing: the Government has proposed new measures such as Customer Correction Notices. They are not yet in force.
1. UK tax is personal: first establish whose income it is
Many families hold accounts and property in different names: accounts a parent opened for a child, a home in joint names, a flat in an older relative’s name with the rent collected by someone else. When a letter arrives, the first question is not “do we owe tax?” but “whose income is this?”
“UK tax is assessed on individuals rather than on the family as a whole. It is therefore important to establish exactly whose income, gains or assets are in question and who is the beneficial owner of them. The person named on a bank account or property record is not always the person who is taxable on the income arising from it.”
Next, compare the records. Hayley Ives says the next step is to compare HMRC’s concerns with the tax returns and supporting records, to establish whether there is actually an error that needs correcting. That determines what next steps are appropriate.
What this means for readers. In Zagdim’s summary: list every account or asset the letter mentions, and note whose name it is in, whose money it really is, and who receives the income. Then find that person’s tax returns for the years concerned. Only after comparing them will you know whether something was left out, reported under the wrong person, or is not a problem at all.
2. If a disclosure is needed: two stages
What the rules say. HMRC’s WDF guidance on GOV.UK sets out:
- Notification: tell HMRC you intend to make a disclosure through the Digital Disclosure Service, and HMRC gives you a disclosure reference number (DRN).
- 90 days: once you have notified HMRC, you have 90 days to gather information, calculate the tax, interest and penalties, and make the disclosure.
- Complex cases: you can ask for 90 extra days, up to 180 days in total. This has to be requested; it is not automatic.
- Payment: the full amount is due when you submit. If you cannot pay at once, agree payment arrangements with HMRC before submitting.
What the expert says. Hayley Ives describes the same process: a disclosure through the WDF generally involves two stages. First, the taxpayer or their agent notifies HMRC through the Digital Disclosure Service. HMRC then issues a disclosure reference number and, in most cases, the taxpayer has 90 days to submit the full disclosure, including calculations of the tax, interest and penalties due.
She adds that HMRC will often allow more time where genuine efforts are being made to gather information, but taxpayers should keep HMRC informed of progress. Silence or missed deadlines are more likely to trigger formal enquiries.
3. How long it really takes: six months to a year
The 90 days is the deadline for submitting the disclosure, not for the whole matter. Hayley Ives says: “In theory, a straightforward disclosure can often be progressed from initial review to HMRC’s first response within around three to five months. In practice, however, many cases take longer, so six months to a year is often more realistic.”
She explains why: overseas records are not always readily available, ownership arrangements may need careful analysis, and HMRC may raise follow-up questions after a disclosure is submitted.
What this means for readers. In Zagdim’s reading, if your records are spread across places, or accounts and property are held in family members’ names, plan for longer than 90 days. You can start now by gathering bank statements, leases and rent records, purchase and sale documents, and transfer records, so you are not chasing overseas banks at the last minute.
4. The rules are changing: Customer Correction Notices
Where things stand. On 13 July 2026, HMRC published the policy paper and draft legislation “Modernising the correction of errors” on GOV.UK (updated 28 October 2026). It includes an obligation on taxpayers to correct errors they identify and a new HMRC power to issue a Customer Correction Notice. This is draft legislation and is not yet law.
What the expert says. Hayley Ives notes that the compliance landscape is continuing to evolve. The Government has proposed further measures, including Customer Correction Notices and a broader obligation on taxpayers to correct inaccuracies. While these are not yet in force, she says the direction is clear: when potential discrepancies are identified, taxpayers are increasingly expected to engage, review their position and take corrective action where appropriate.
5. What readers can do now
- When a letter arrives, note the reply deadline and work out which family member, and which accounts or assets, it concerns.
- For each account and property, write down whose name it is in, who really owns it and who receives the income.
- Find that person’s tax returns for the years concerned and compare them with HMRC’s concerns.
- If a disclosure is needed, allow at least six months, and a year if records are overseas or ownership is complicated.
- Keep in contact with HMRC throughout. Do not go silent or miss deadlines.
Whether a disclosure is needed also depends on which basis of taxation was used in each year. See Zagdim’s companion interview: Got an HMRC Letter About Overseas Income? A Tax Partner Says Check Which Basis of Taxation You Used First.
If you live in the UK, your family has accounts or property elsewhere, and you are unsure how to handle a letter, you can tell the Zagdim reader desk about your situation. The reader desk will understand your needs and shortlist suitable professionals.
Glossary
- Beneficial owner: the person who actually enjoys an asset and its income, who may not be the name on the record.
- Worldwide Disclosure Facility (WDF): HMRC’s route for voluntarily disclosing tax owed in connection with offshore matters.
- Digital Disclosure Service: HMRC’s online service for notifying an intention to disclose and submitting the disclosure.
- Disclosure reference number (DRN): the number HMRC issues after you notify it that you intend to make a disclosure.
- Customer Correction Notice: a proposed new measure, not yet in force, under which HMRC could ask a taxpayer to check a return it suspects is inaccurate and either correct it or explain why no correction is needed.
About this article
Facts were checked on 20 November 2026. Official rules are based on HMRC’s WDF guidance on GOV.UK (updated 6 April 2026), HMRC’s policy paper “Modernising the correction of errors” (published 13 July 2026, updated 28 October 2026) and HMRC’s 2024–25 annual report. The “what this means for readers” passages in sections 1 and 3 and the checklist in section 5 are Zagdim’s own summary and reading, not the expert’s words.
The expert’s views come from Zagdim’s interview with Hayley Ives (written reply of 3 November 2026). Quotes and paraphrases were confirmed by her before publication. This article is not individual tax advice. Whether you need to make a disclosure, and how many years it covers, depends on your residence history, income and past returns. Check HMRC’s latest guidance and consult a qualified UK tax professional.
Experts interviewed
Hayley Ives|Partner, Tax Disputes & Investigations, Crowe U.K. LLP
References
GOV.UK, “Make a disclosure using the Worldwide Disclosure Facility” (HMRC) / GOV.UK, “Modernising the correction of errors” (HMRC) / HMRC, “HMRC annual report and accounts 2024 to 2025”