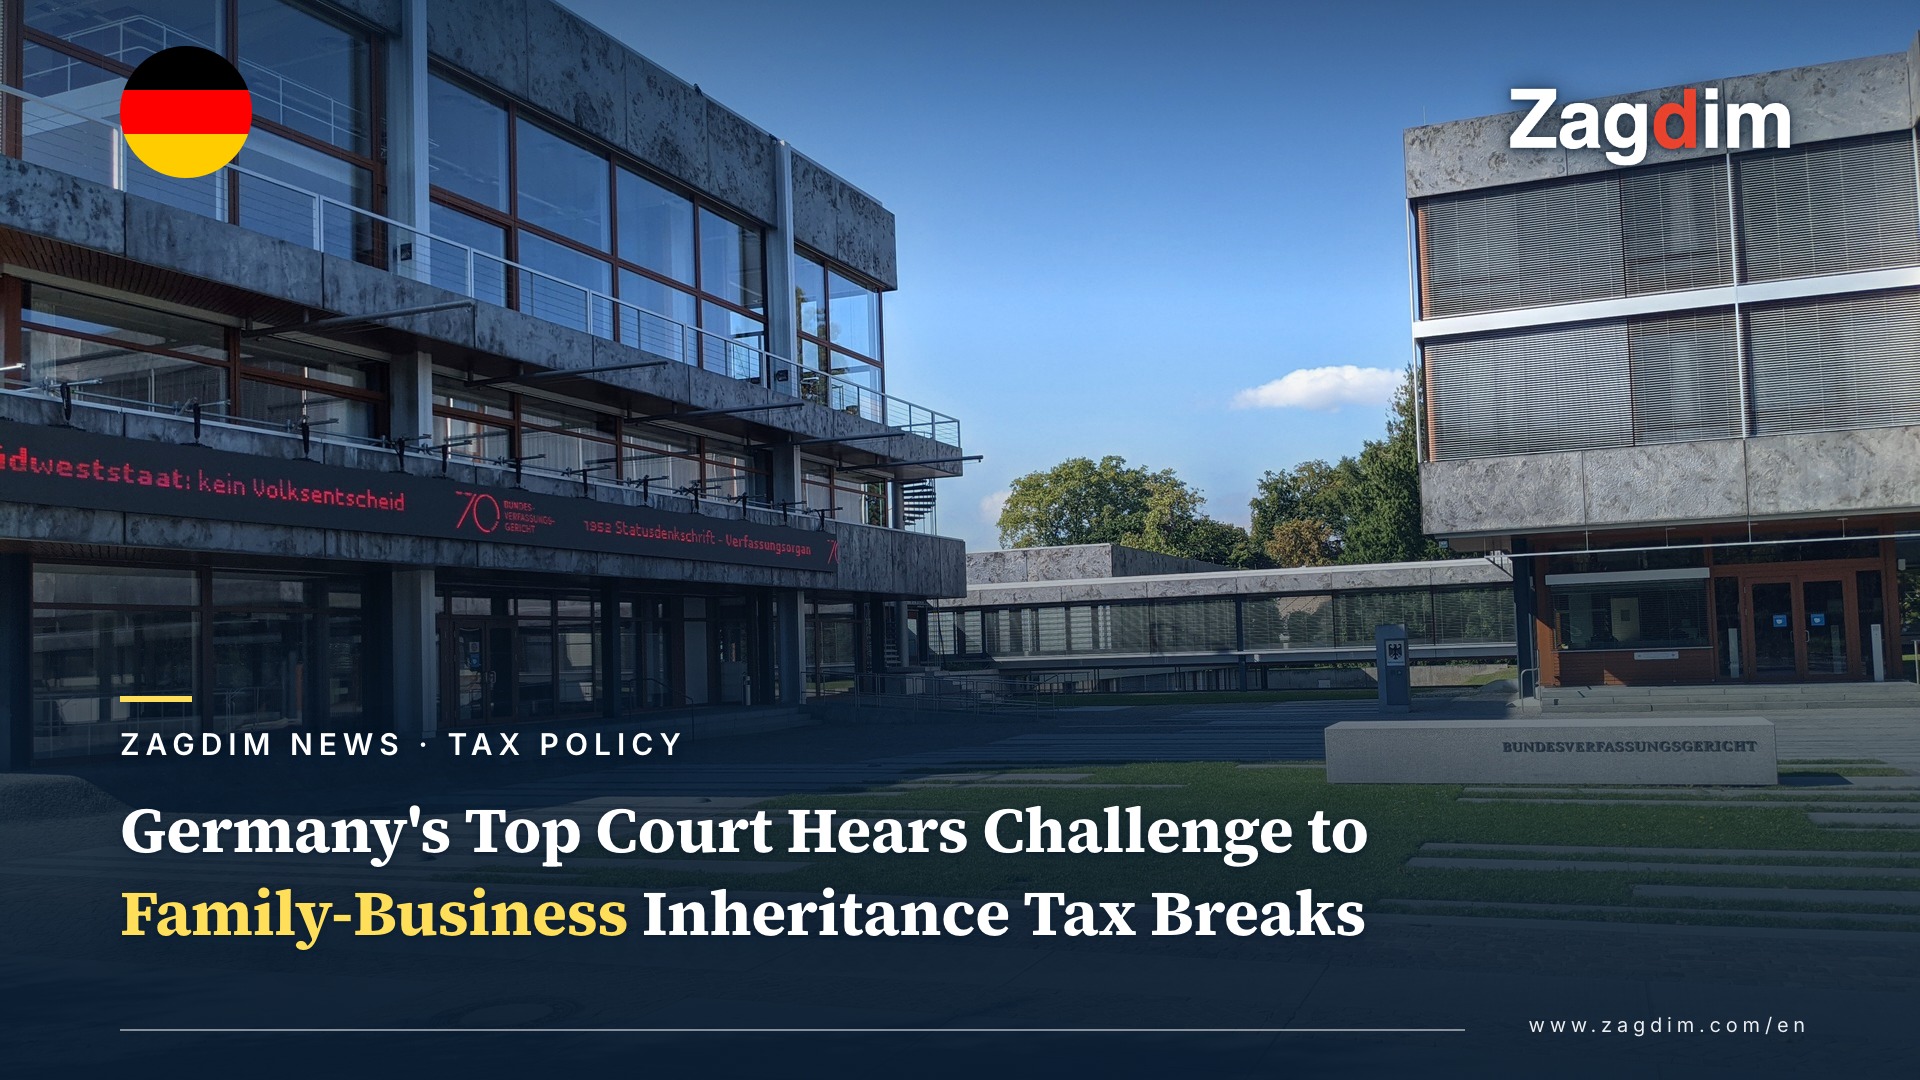
Germany’s Federal Constitutional Court (Bundesverfassungsgericht) opened a hearing on October 13 into whether the country’s preferential tax treatment of inherited family-business shares is constitutional, a case that could reshape succession planning for anyone holding business assets in Germany.
The First Senate of the court, sitting in Karlsruhe under case number 1 BvR 804/22, is reviewing a constitutional complaint (Verfassungsbeschwerde) filed by a man who inherited exclusively private assets — a securities portfolio and real estate — from his aunt. According to the court’s own announcement, he unsuccessfully challenged the inheritance-tax bill on that private-asset inheritance through the lower courts before bringing his case to Karlsruhe. His argument, per Reuters: he was taxed at a higher rate on his private inheritance than would have applied had the same value been held as qualifying business assets instead. The complaint is directed against his own tax assessment and, indirectly, against several provisions of Germany’s Inheritance and Gift Tax Act (Erbschaft- und Schenkungsteuergesetz, ErbStG) and one provision of the Valuation Act (Bewertungsgesetz).
At issue is Germany’s tiered relief regime for inherited business assets. Private assets, including an inheritance like the plaintiff’s, can be taxed at up to 50% depending on the heir’s relationship to the deceased and the value involved. Business assets, by contrast, can qualify for significant relief: 85% can stay tax-free if the heir keeps the business running for at least five years without cutting payroll too sharply, rising to a full 100% exemption if the business is held for at least seven years. For transfers of business assets above roughly €26 million, a separate “needs-based exemption test” (Verschonungsbedarfsprüfung) can waive the tax entirely if the heir can show they cannot pay it out of their own available assets. Germany’s Federal Statistics Office says the state forfeited €3.7 billion in revenue last year after 34 heirs had a large portion of their inheritance tax waived, Reuters reported.
Representing the roughly 20 associations, institutes, academics and organisations invited to the hearing, Monika Wünnemann of Germany’s BDI industry association defended the current rules, telling the court that “the differences in the taxation of business assets and private assets are objectively justified,” and that inheritance tax must otherwise be paid out of profit distributions in a way that weakens a company’s investment capacity. A representative of the finance ministry separately defended the 2016 version of the law — itself written in response to an earlier 2014 constitutional-court ruling that struck down the previous, more generous privileges for very large business transfers — as consistent with that court’s past guidance. Mittelstand associations, representing family-owned firms that make up around 99% of German companies, argue that narrowing the exemption further could hurt investment and cost jobs at a time when Europe’s largest economy is already struggling to regain momentum.
The court is expected to rule in the coming months, according to Reuters and German public broadcaster ARD. A ruling against the current rules would not, on its own, change anyone’s tax bill immediately — but it would put Germany’s legislature back in the position it was in after the 2014 ruling: required to rewrite the relief rules for inherited business assets within a court-set deadline. Anyone with German business assets, or succession plans built around the current five- and seven-year continuation rules, is in a holding pattern tied to this case until the court rules.
References
Yahoo Finance UK (Reuters) – German Family-Owned Firms Face Inheritance Tax Challenge / Bundesverfassungsgericht – Mündliche Verhandlung in Sachen „Erbschaftsteuer – Verschonung von Betriebsvermögen” am Dienstag, den 13. Oktober 2026, 10.00 Uhr / tagesschau.de (ARD) – Die Erbschaftsteuer auf dem Prüfstand