Selling a Mortgaged Property in Dubai: Get the Bank’s Approval, Then Clear the Loan by Manager’s Cheque at DLD
Selling a mortgaged property in Dubai is allowed, but under Article 10 of Dubai Law No. 14 of 2008 on mortgages, the sale needs the approval of the mortgagee, which is the lending bank. The usual route is to clear the loan from the sale price: at a Dubai Land Department (DLD) trustee office, manager’s cheques pay the bank, the seller and DLD, and the transfer completes once the bank issues a mortgage release letter.
A Khaleej Times legal column published on 25 October 2026 answered a reader who had lost their job in Dubai, planned to return home and still had a mortgage on the property. The reader wanted to know whether they could sell, whether the buyer could take over the remaining loan, and whether the bank had to approve. According to the report, lawyer Ashish Mehta cited Article 10 and set out two routes: settle the mortgage from the sale proceeds, or ask the bank whether the buyer can assume the existing loan.
This guide does not give legal advice. It uses DLD’s official service pages, the text of the Dubai mortgage law and the fee caps set by the Central Bank of the UAE (CBUAE) to explain the steps, the documents, how the money moves, and what owners living in Dubai, owners living abroad and buyers each need to watch.
Key Points
- Who should pay attention: owners in Dubai who still have a mortgage and plan to leave the UAE or move home; owners abroad who need someone to sell for them; and buyers looking at a property that still has a mortgage on it.
- The legal starting point: Article 10 of Dubai Law No. 14 of 2008 says a mortgaged property can be sold only with the bank’s approval, and the buyer must agree to take on the owner’s obligations under the mortgage contract. The bank may also make seller and buyer jointly liable.
- The usual process: get a liability letter from the bank, sign the sale contract and get the developer’s e-NOC, go to a DLD trustee office with three manager’s cheques (to the bank, to the seller and to DLD), collect the bank’s release letter, and DLD completes the release, transfer and any new mortgage.
- Costs: the DLD transfer fee is 4% of the sale price (listed by DLD as 2% each for seller and buyer). The CBUAE caps home loan early settlement fees at 1% of the outstanding balance or AED 10,000, whichever is lower. Release, registration and service partner fees also apply.
What the Law Says About Selling a Mortgaged Property in Dubai: Article 10 Requires Bank Approval
Mortgages over Dubai property are governed by Law No. 14 of 2008 Concerning Mortgages in the Emirate of Dubai. Article 4 says the mortgagee must be a bank or a financing company licensed and registered with the Central Bank of the UAE to provide property finance in the UAE. In other words, the lender behind your home loan is the mortgagee on your property.
Article 10 is the key rule when you sell. It says a mortgagor may sell, donate or otherwise dispose of the mortgaged property only with the approval of the mortgagee, and only if the person receiving the property agrees that all of the mortgagor’s obligations under the mortgage contract pass to them. The mortgagee may also state in the mortgage contract that the mortgagor and that person are jointly liable for those obligations.
The law allows a buyer to take on the obligations, but there is a simpler route: clear the loan on the day of transfer, release the mortgage, and let the buyer pay in cash or with a new mortgage of their own. DLD has a dedicated service for this, Registering the Sale of a Mortgaged Property. Its service page says the bank’s dues are paid and both parties’ rights are reserved first, and the sale is completed once the seller submits the bank’s mortgage release letter.
Two Routes: Settle From the Sale Price, or Let the Buyer Assume the Loan
The two routes below are based on the Khaleej Times legal column of 25 October 2026 and its reading of Article 10 (according to the report; which route a bank accepts depends on the bank’s written reply):
| Route | How it works | What to watch |
|---|---|---|
| Settle the loan from the sale price | The bank issues a liability letter; both parties go to a DLD trustee office and clear the loan by manager’s cheque; the bank issues a release letter and DLD completes the release and transfer | DLD has a dedicated service for it; work out the early settlement fee first, because the seller receives the sale price minus the debt |
| Let the buyer assume the existing loan | The seller asks the bank whether the buyer can take over; the bank assesses the buyer’s finances and may require new or revised financing documents | Needs the bank’s written approval and registration in line with bank and DLD requirements; the bank can say no |
A seller can also pay off the mortgage with their own funds first, get the release, and then sell as a normal transfer. That keeps transfer day simpler, but it needs enough cash upfront to clear the loan.
Selling a Mortgaged Property in Dubai: Five Steps
The five steps below come from DLD’s official service pages, Registering the Sale of a Mortgaged Property and Property Sale Registration (accessed 10 November 2026):
| Step | What happens | Who |
|---|---|---|
| 1. Get bank approval and a liability letter | Ask your lender for a liability letter showing the outstanding balance, the settlement amount and any early settlement and other fees; for an off-plan unit with money still owed to the developer, the developer issues a letter instead | Seller |
| 2. Sign the sale contract and get the developer e-NOC | Agree the price and payment arrangements; in freehold areas, the developer’s electronic no-objection certificate (e-NOC) is requested through the Dubai REST app | Seller, buyer |
| 3. Register at a DLD trustee office | Both parties bring ID, the liability letter and three manager’s cheques to a Real Estate Registration Trustee centre; the registrar checks documents and enters the transaction, and the payment receipt arrives by email; the visit takes about 15 to 20 minutes | Seller, buyer |
| 4. Seller takes the debt cheque to the bank | After DLD’s audit, both parties receive a registration certificate by email and the seller receives the cheque for the bank, pays off the loan and obtains a mortgage release certificate | Seller |
| 5. DLD completes registration | Once the seller or buyer submits the release letter, DLD completes the mortgage release, the sale and, if the buyer is borrowing, the new mortgage | Seller or buyer |
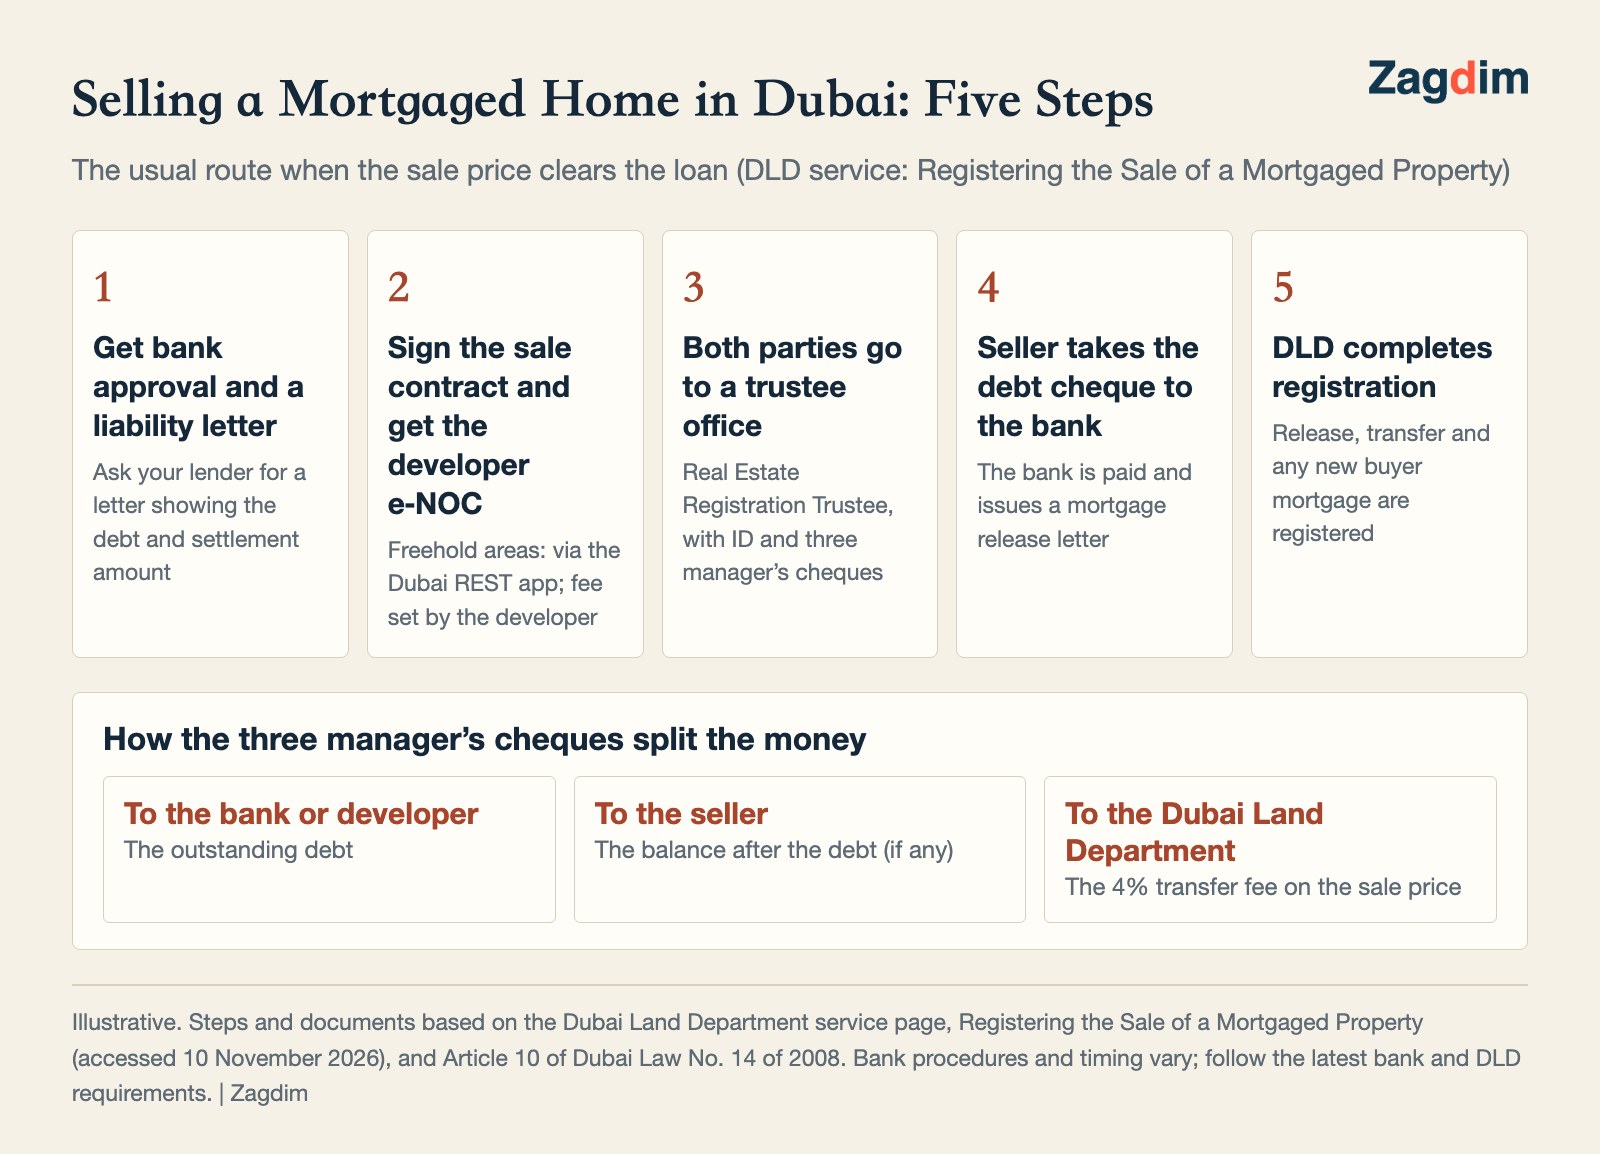
DLD’s service page lists UAE citizens, residents and tourists as eligible, so non-resident foreigners can use a valid passport. The only channel is a Real Estate Registration Trustee centre.
Documents You Need, and How the Three Cheques Split the Money
DLD’s service page lists these documents for individual sellers and buyers:
- A liability letter from the bank, or a letter from the developer stating the remaining amount.
- The UAE ID of the seller and the buyer (for identification only; no copy is kept), or a valid passport for non-resident foreigners.
- Three manager’s cheques: one to the bank or developer for the debt, one to the seller for the remaining balance (if any), and one to DLD for the 4% fee.
- A legal power of attorney if someone is acting on a party’s behalf.
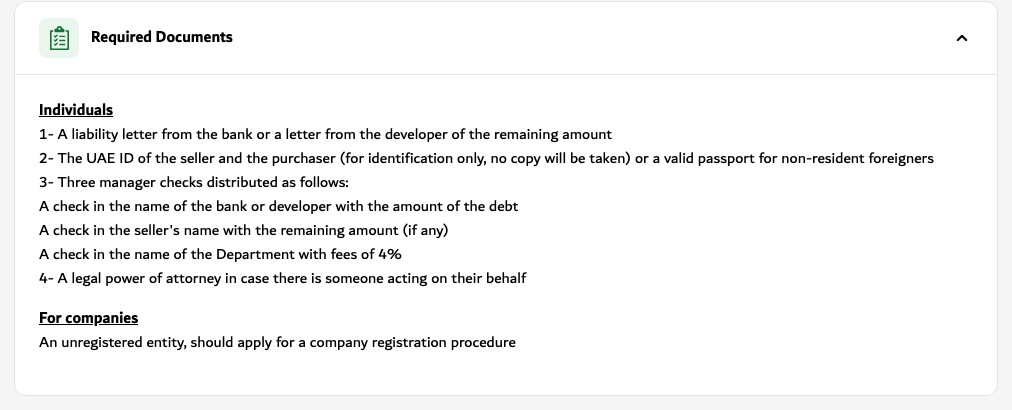
For property held by a company, DLD asks an unregistered entity to complete a company registration first. Where an off-plan buyer still owes the developer instalments, the developer’s letter can replace the bank’s liability letter, but check the developer’s resale conditions first.
Fees When Selling a Mortgaged Property in Dubai
Costs fall into two groups: DLD registration fees and the bank’s settlement-related fees. The DLD amounts come from the official service pages, Registering the Sale of a Mortgaged Property and Property Sale Registration. The bank fees are maximums set by the CBUAE, not fixed charges:
| Fee | Amount | Basis |
|---|---|---|
| DLD transfer fee | 4% of the sale price (listed by DLD as 2% seller, 2% buyer) | DLD |
| Mortgaged-sale registration fee | AED 1,000, plus AED 10 knowledge fee and AED 10 innovation fee | DLD |
| Mortgage release fees | AED 1,290, plus AED 315 registrar fee for the release | DLD |
| Sale registrar (service partner) fee | Sale price under AED 500,000: AED 2,100; AED 500,000 or more: AED 4,200 | DLD |
| Title deed and map | Title deed AED 250; map for an apartment or villa AED 250 | DLD |
| Buyer’s new mortgage registration | 0.25% of the loan amount (if the buyer borrows) | DLD |
| Home loan early settlement fee | Capped at 1% of the outstanding balance or AED 10,000, whichever is lower | CBUAE |
| Bank liability letter | Capped at AED 85 | CBUAE |
| Bank NOC and clearance letter | Capped at AED 150 and AED 95 | CBUAE |
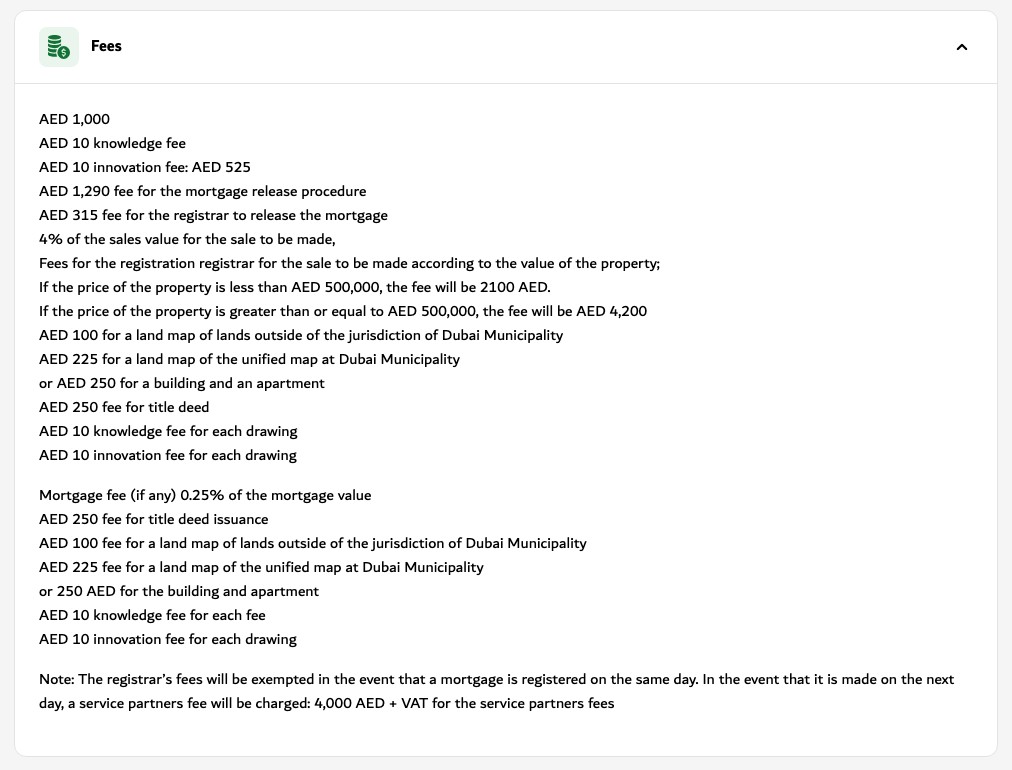
A few details matter:
- Who pays the 4%: DLD lists 2% each for seller and buyer; who actually pays is set in the sale contract.
- CBUAE caps exclude VAT: CBUAE Notice N 3986/2019 (effective 8 October 2019) amended Appendix 2 of Regulation 29/2011. All fees in it exclude VAT, and the same document says the caps are maximums; a bank whose costs are lower should charge less.
- Register the new mortgage the same day: DLD notes that the registrar fee is waived if the buyer’s mortgage is registered on the same day. If it is registered the next day, a service partner fee of AED 4,000 plus VAT applies.
- Developer e-NOC fees: each developer sets its own fee. DLD does not list an amount, so ask the developer.
What Each Type of Reader Needs to Do
Owners Living in Dubai
Start by asking your bank for an up-to-date liability letter showing the outstanding balance, early settlement fee and other charges. Then take your expected sale price, subtract the debt and the fees, and see what you will actually receive. The early settlement fee is subject to the CBUAE cap, and the same cap applies to partial settlement.
If the property is let, Article 28 of Dubai Law No. 26 of 2007 says a transfer of ownership does not affect the tenant’s right to stay under a fixed-term lease, so the new owner becomes the landlord. Getting a tenant to leave means following the notice rules in the tenancy law; see Dubai Landlord Selling the Flat? Your 12-Month Notice and Tenant Rights Explained.
If you are leaving the UAE, deal with other loans and credit cards as well as the mortgage. For how debts and credit records follow you, see How the UAE Credit Score Works: What Credit Score 3i Means for Foreign Residents.
Owners Living Abroad: Selling Through a Power of Attorney
DLD’s service page says a legal power of attorney is needed when someone acts on a party’s behalf. BSA Law explains that DLD Circular No. 29/R/2025, issued on 16 July 2025, sets four conditions for a power of attorney issued outside the UAE:
- It must have been issued within the 2 years before it is submitted.
- It must be notarised by the competent authority in the issuing country, legalised by a UAE embassy or consulate there, and then attested by the UAE Ministry of Foreign Affairs.
- The original must be presented; uncertified electronic or scanned copies are not accepted.
- If it is not in Arabic, it needs a full legal translation by a UAE-licensed translator.
These conditions are as explained by the law firm; check the circular itself through DLD. The power of attorney should cover selling this specific property, dealing with the bank on settlement and release, and receiving the sale proceeds. Also ask your bank in advance whether it will deal with an attorney for the payoff and release.
Buyers: Paying Cash or Borrowing
A buyer can pay in cash or with a new mortgage. DLD’s process only requires the cheque to the bank to match the debt; where the money comes from is up to the buyer:
- Paying cash: the buyer’s funds are split into the debt cheque to the seller’s bank and the balance cheque to the seller, plus DLD fees.
- Borrowing as well: the buyer’s new loan can fund the debt cheque to the seller’s bank. Ask your lender who issues the cheque and when the loan is released. The release, transfer and new mortgage are registered together at DLD, and the new mortgage costs 0.25% of the loan to register.
Before registration, a buyer can check three things: the amount on the seller’s liability letter matches the cheque, the developer e-NOC has been issued, and their own lender accepts this kind of mortgaged-property sale. If you are planning to buy in Dubai, see How to Buy Property in Dubai as a Foreigner: Process, Eligibility and Legal Guide.
Common Misconceptions About Selling a Mortgaged Property in Dubai
- “You can’t sell a home that still has a mortgage”: you can, but the bank must approve. The usual route is to clear the loan from the sale price on transfer day.
- “The buyer can simply take over my mortgage”: Article 10 allows a buyer to assume the obligations, but only with bank approval, and the bank will assess the buyer. The usual route is to settle the old loan while the buyer takes out their own mortgage.
- “Paying off a mortgage early costs a fortune”: the CBUAE caps home loan early settlement fees at 1% of the outstanding balance or AED 10,000, whichever is lower, excluding VAT.
- “The buyer always pays the 4% fee”: DLD lists 2% each for seller and buyer; who pays is set in the sale contract.
- “If you live abroad, you must fly back to Dubai”: you can act through a power of attorney, but one signed abroad must be notarised, legalised and attested, with a legal Arabic translation.
Scenarios: How Three People Sell or Buy
Scenario one: an owner whose Dubai job has ended and who is moving back to Asia
His flat still has a mortgage. He asks the bank for a liability letter to confirm the outstanding balance and early settlement fee, deducts the estimated DLD fees to see what he will receive, and then sets an asking price. He puts what must happen before he leaves in order: sign the contract, get the developer e-NOC, register at the trustee office, collect the release letter to complete the transfer, and only then close his accounts.
Scenario two: an owner in Taiwan with a let flat in Dubai
She does not plan to fly out. In Taiwan she signs a power of attorney specifically for selling this flat, has it notarised and legalised by the UAE mission, sends it to Dubai for UAE foreign ministry attestation and an Arabic translation. The flat has a tenant on a fixed-term lease, so her sale contract states that the flat is sold with the lease and the new owner becomes the landlord.
Scenario three: a buyer who is also borrowing
He likes a flat that still has a mortgage. He first checks that his own lender can handle a mortgaged-property sale, then matches the amount on the seller’s liability letter. His new loan funds the cheque to the seller’s bank, and the release, transfer and his new mortgage are registered on the same day, avoiding the extra service partner fee for next-day registration.
Selling a Mortgaged Property in Dubai: FAQ
Do I need the bank’s approval to sell a mortgaged property in Dubai?
Yes. Article 10 of Dubai Law No. 14 of 2008 says a mortgaged property can be sold only with the mortgagee’s approval, and the buyer must agree to take on the owner’s obligations under the mortgage contract. The usual route is to clear the loan from the sale price on transfer day and complete the transfer once the bank issues a release letter.
How much is the early settlement fee on a Dubai mortgage?
CBUAE Notice N 3986/2019 caps the early or partial settlement fee on home loans at 1% of the outstanding balance or AED 10,000, whichever is lower, excluding VAT. It is a maximum, so banks can charge less; the amount will appear on your bank’s liability letter.
Who pays the 4% DLD fee when selling in Dubai?
DLD’s Property Sale Registration page lists 2% for the seller and 2% for the buyer. Who actually pays depends on the sale contract. In a mortgaged-property sale, the 4% is paid at the trustee office by a manager’s cheque made out to DLD.
Is selling a mortgaged property in Dubai possible if I live abroad?
Yes, through an attorney. DLD’s service page requires a legal power of attorney when someone acts on your behalf. A law firm explains that a DLD circular of July 2025 requires a power of attorney issued abroad to be issued within 2 years, notarised, legalised by the UAE embassy and attested by the UAE foreign ministry, legally translated into Arabic, and presented in original.
How does the process change if the buyer is also taking a mortgage?
The buyer’s new loan can fund the debt cheque to the seller’s bank. Once the seller’s bank issues the release letter, DLD registers the release, the transfer and the buyer’s new mortgage together. The new mortgage costs 0.25% of the loan to register, and the registrar fee is waived if it is registered the same day. Ask the buyer’s lender about cheque and drawdown timing.
What documents do I need when selling a mortgaged property in Dubai?
DLD’s service page lists a liability letter from the bank (or a developer’s letter of the remaining amount), UAE ID for both parties or a valid passport for non-residents, three manager’s cheques (to the bank, to the seller and to DLD), and a power of attorney if someone is acting for you. Freehold properties also need the developer’s e-NOC.
Selling a Home in Dubai? Ask Zagdim
If you want to work out what you would receive after the mortgage and fees, or how to arrange a power of attorney from abroad, start with Ask Zagdim.
Life abroad? Ask Zagdim.
Your first stop for international property and global living.
Research and insights. Know what’s changing. Understand what matters.
Newsletter for overseas updatesSubscribe →
Important Disclaimer
This article is general information, not legal, tax or financial advice, and it does not represent any decision by a bank, developer or the Dubai Land Department on an individual transaction. The Khaleej Times legal column is summarised as reported by the media, and the conditions for powers of attorney from abroad are as explained by a law firm. Fees and procedures are based on DLD service pages, Dubai Law No. 14 of 2008 and CBUAE notices, and may change. Follow the latest official notices, your bank’s written answers and your sale contract, and consult a lawyer licensed in the UAE where needed.
Rules and fees in this article are current as of 10 November 2026; check the latest notices from the Dubai Land Department and the Central Bank of the UAE. Next review: when DLD changes its sale or mortgage release fees, or the CBUAE revises its home loan fee caps.
References
Dubai Land Department – Registering the Sale of a Mortgaged Property / Dubai Land Department – Property Sale Registration / Dubai Legislation Portal – Law No. (14) of 2008 Concerning Mortgages in the Emirate of Dubai / Central Bank of the UAE Rulebook – Notice N 3986/2019, Amending Appendix 2 of Regulation No. 29/2011 / Khaleej Times – Selling a mortgaged property in Dubai? Rules, transfer options explained (25 October 2026) / BSA Law – Dubai’s new standards for powers of attorney in property deals (19 August 2025)