

































How Does Japan Consumption Tax Work Now? 8% and 10% Are in Force, While the 1% Food Rate Is Still a Bill (19 October 2026)
Japan consumption tax currently has two rates: according to the National Tax Agency’s Tax Answer No. 6102, groceries and takeout are taxed at 8%, while dining in and alcohol are taxed at 10%.
On 9 October 2026, Japan’s Cabinet approved a bill to cut the consumption tax rate on food and non-alcoholic drinks from 8% to 1% and submitted it to the Diet the same day. NHK and Jiji Press reported on 16 October 2026 that the House of Representatives is scheduled to begin debating it in plenary session on 20 October, and that the ruling side is aiming to pass it before the session ends on 12 December. This guide was written on 19 October 2026, before debate had started.
The guide therefore has two parts. The current 8% and 10% rules are in force and are stated as fact. The 1% food rate is only a bill: it has not passed, and its content and timetable could change. Everything about it is placed under “if the bill passes”.
Key Points
- Who needs to take note: foreign residents, workers and visitors in Japan who buy groceries, convenience-store meals and restaurant meals every day, and foreign owners of restaurants or food shops in Japan.
- Rules in force today: groceries, takeout and delivery are taxed at 8%. Dining in at a restaurant, the eat-in area of a convenience store, catering at your home and alcohol are taxed at 10%.
- The bill, not yet passed: from 1 April 2027 to 31 March 2029, food would be taxed at 1%. Dining in and alcohol would stay at 10%. If it passes, the gap between taking a meal away and eating it in would widen from 2 percentage points to 9.
- The easiest thing to get wrong: the rate depends on how the food is provided, not on which shop you buy from. One convenience store can charge two different rates.
Japan Consumption Tax at 8% and 10% Today: Takeout, Dine-In, Delivery and Alcohol Compared (In Force)
The table below follows the National Tax Agency’s Tax Answer No. 6102 (law as of 1 April 2026) and its Q&A on the reduced-rate system, individual cases edition (revised April 2026). The “Basis” column gives the item that supports each row:
| Situation | Rate | Basis |
|---|---|---|
| Groceries and non-alcoholic drinks from a supermarket or shop | 8% | No. 6102 |
| Eating in at a restaurant or café | 10% | No. 6102, note 3 |
| Restaurant takeout (持ち帰り) | 8% | Q&A 58 |
| Delivery, such as soba or pizza simply brought to the place you specify | 8% | Q&A 77 |
| Convenience-store meal served on a tray or reusable dishes in the eat-in area | 10% | Q&A 52 |
| The same convenience-store meal taken away | 8% | Q&A 52 |
| Food-court meals, where the operator and facility agree customers use the tables | 10% | Q&A 65 |
| Street stalls: with their own tables or permitted use of tables; with no tables or only public benches | 10%; 8% | Q&A 51, 65 |
| A cook preparing food at your home, and other catering (ケータリング) | 10% | No. 6102; Q&A 76 |
| Drinks and snacks from vending machines | 8% | Q&A 33 |
| Dining car on a train; trolley sales of bento and drinks on board | 10%; 8% | Q&A 69 |
| Hotel room service; non-alcoholic drinks from the in-room fridge | 10%; 8% | Q&A 72, 73 |
| Alcohol (beer, sake, wine, みりん and other drinks of 1% alcohol by volume or more) | 10% | Q&A 12–14 |
| Alcohol-free beer and amazake (under 1% alcohol) | 8% | Q&A 15 |
| Energy drinks: those classed as medicines or quasi-drugs; those that are not | 10%; 8% | Q&A 23 |
| Newspapers on regular subscription (published at least twice a week) | 8% | No. 6102 |
One line runs through the whole table. Food sold to you as a product is taxed at 8%. A meal provided in a place with seating, as a service, is taxed at 10%. Alcohol is outside the 8% rate however you buy it.
How a Convenience Store Decides Whether You Are Eating In or Taking Away
Q&A 52 explains that the rate is decided when the shop hands over the food, by confirming with the customer. A convenience store that sells mostly takeaway items does not have to ask every customer; it can instead post a notice such as “イートインコーナーを利用する場合はお申し出ください” (please tell us if you will use the eat-in corner). In practice, if you buy a hot meal or a bento at a Japanese convenience store and want to eat it in the eat-in area, tell the cashier at checkout.
Why Prices in Japanese Shops Already Include Tax
Under the current rules, shops that display prices to consumers in advance must show the tax-inclusive price (総額表示; page 7 of the National Tax Agency’s tax-cut pamphlet). The price tag is therefore normally the amount you pay at the till. That habit matters for the price-display transition described below.
The Bill to Cut Food to 1%: Scope, Period and Where It Stands (Not Yet Passed)
Where the Bill Stands
The bill’s official title is “租税及び社会保険料による負担の軽減のための飲食料品に係る消費税率の臨時的な引下げ及び就業者負担軽減支援金の支給に関する法律案“. It is a Cabinet bill, to be considered first by the House of Representatives. According to the House of Councillors’ bill information page (as of 13 October 2026), it was submitted on 9 October 2026 and every deliberation-progress field was still blank. The table separates official sources from press reports; every future date is a plan and could shift:
| Date | Event | Basis |
|---|---|---|
| 15 September 2026 | Cabinet approves the outline for a temporary cut in the consumption tax rate on food and a support payment for workers; the National Tax Agency opens a tax-cut special website | National Tax Agency special website |
| 9 October 2026 | Cabinet approves the bill and submits it to the Diet, House of Representatives first | House of Councillors bill information; NHK, 9 October 2026 |
| 20 October 2026 (planned) | House of Representatives begins debate in plenary session; the Prime Minister is expected to attend questioning | NHK and Jiji Press, 16 October 2026 |
| Early November 2026 (planned) | The ruling side hopes the House of Representatives will pass it; press reports say it intends to send it to the House of Councillors in the first half of November | Jiji Press and Kyodo, 16 October 2026 |
| 12 December 2026 | End of the extraordinary Diet session; the ruling side aims to pass the bill by then | Jiji Press, 16 October 2026 |
To become law the bill must still pass both houses, and the outcome is not known. Kyodo News reported on 9 October 2026 that this would be the first cut in the consumption tax rate since the tax was introduced in 1989, and that deciding how to fund the roughly ¥10 trillion cost over two years was put off in this proposal. Whether the funding plan will affect the bill is impossible to say now.
If the Bill Passes: Period, Rate and Scope
The following is based on the leaflet and pamphlet the National Tax Agency published in September 2026. All of it assumes that the bill is submitted to the Diet and passes after deliberation:
- Period: 1 April 2027 to 31 March 2029, two years.
- Rate: food and drink 1% (0.78% national consumption tax plus 0.22% local consumption tax); subscription newspapers stay at 8%; everything else stays at 10%.
- From 1 April 2029: the agency’s pamphlet gives an example in which food sales from 1 April 2029 are again taxed at 8%.
- Scope: the same as what is taxed at 8% on or before 31 March 2027. It is not a new set of definitions.
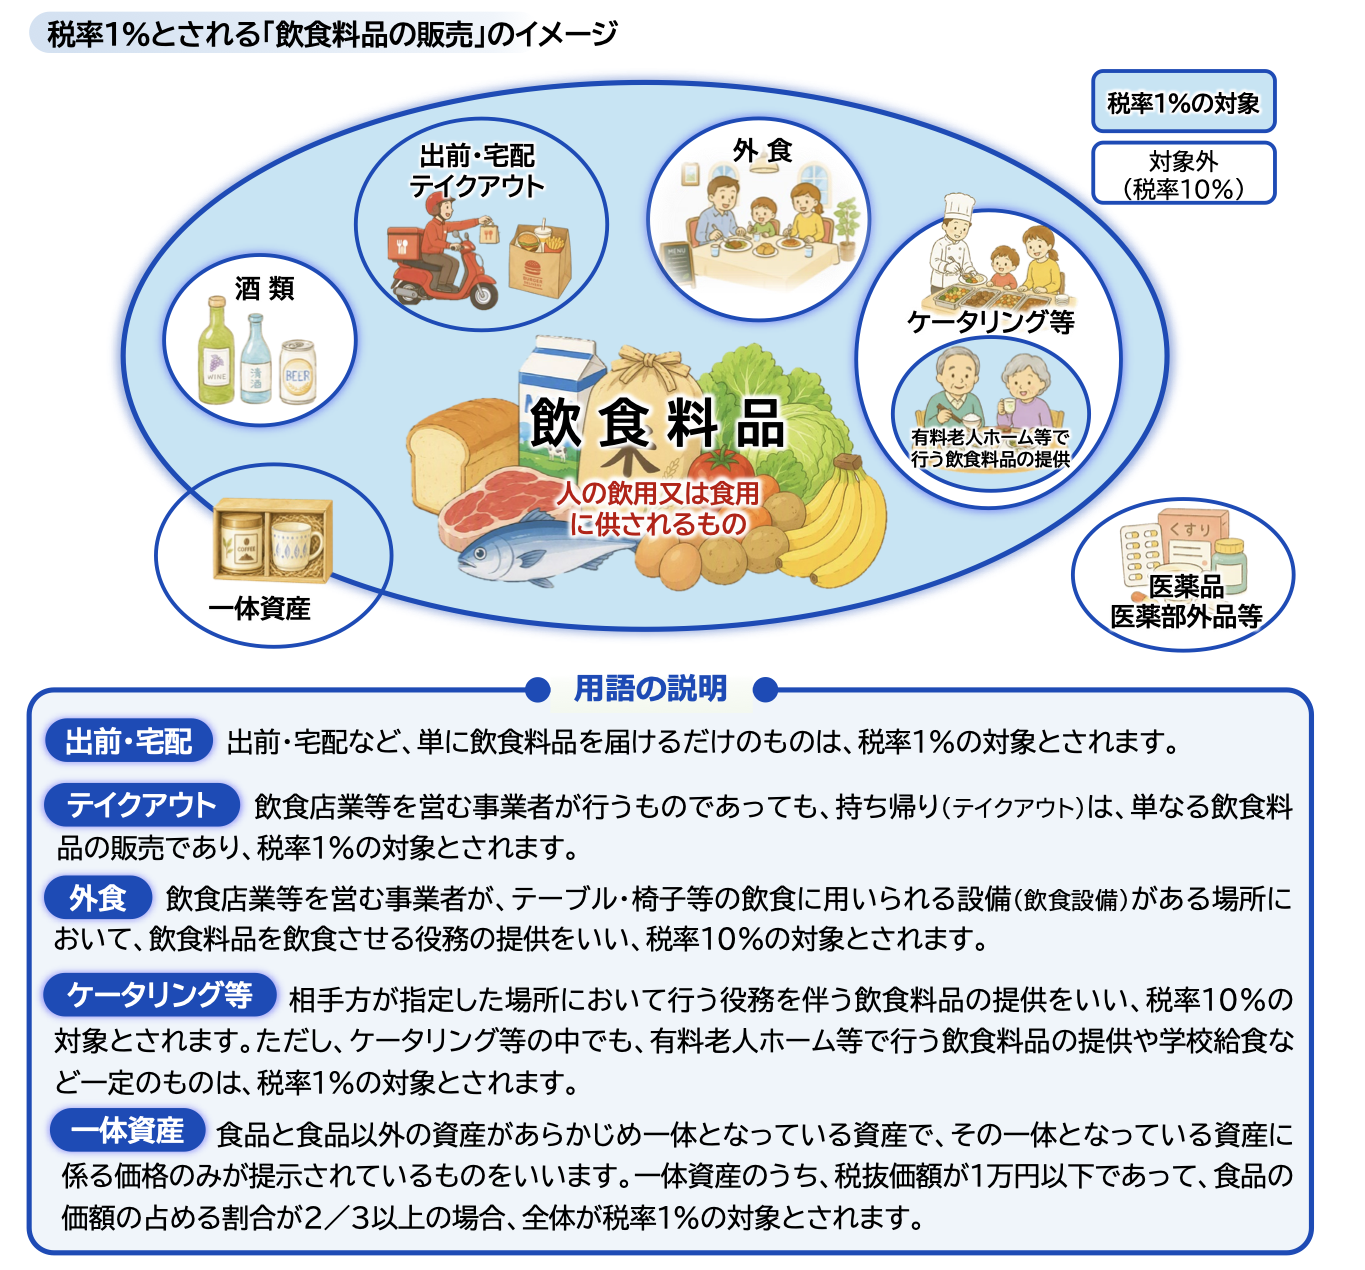
Because the scope follows the current 8% rules, the “8%” rows of the table above would read “1%” if the bill passes, and the “10%” rows would stay as they are. The “In force” column follows Tax Answer No. 6102 and the individual-cases Q&A; the “If the bill passes” column follows the agency’s leaflet and pamphlet of September 2026:
| Situation | In force today | If the bill passes (1 April 2027 to 31 March 2029) |
|---|---|---|
| Groceries and non-alcoholic drinks | 8% | 1% |
| Restaurant takeout | 8% | 1% |
| Delivery | 8% | 1% |
| Eating in at a restaurant or café | 10% | 10% |
| Convenience-store eat-in area | 10% | 10% |
| Catering at your home | 10% | 10% (1% in certain cases, such as meals served at fee-charging care homes and school lunches) |
| Alcohol | 10% | 10% |
| Medicines and quasi-drugs | 10% | 10% |
| Newspapers on regular subscription | 8% | 8% |
What a Bento Takeaway and Eat-In Would Cost (Zagdim Calculation)
Suppose a bento costs ¥500 before tax. Zagdim calculated with the rates published by the National Tax Agency (8% and 10% today, 1% under the bill):
| Situation | In force today | If the bill passes |
|---|---|---|
| Takeaway | ¥540 (8%) | ¥505 (1%) |
| Eat-in | ¥550 (10%) | ¥550 (10%) |
| Eat-in minus takeaway | ¥10 (a 2-percentage-point gap) | ¥45 (a 9-percentage-point gap) |
This is illustrative arithmetic. Actual prices, rounding and shop pricing are set by each shop, and the official announcements govern.
Price Display During the Transition: Shelves May Still Show Old Prices From February to May 2027, If the Bill Passes
Replacing every price tag on the day a rate changes is hard. The special rule on page 7 of the agency’s pamphlet is this: if the bill passes, from 1 February to 31 May 2027 a shop that has difficulty adjusting may keep showing food prices including 8% tax, or switch to prices including 1% tax, or mix the two, as long as it displays a notice that prevents customers from being misled.
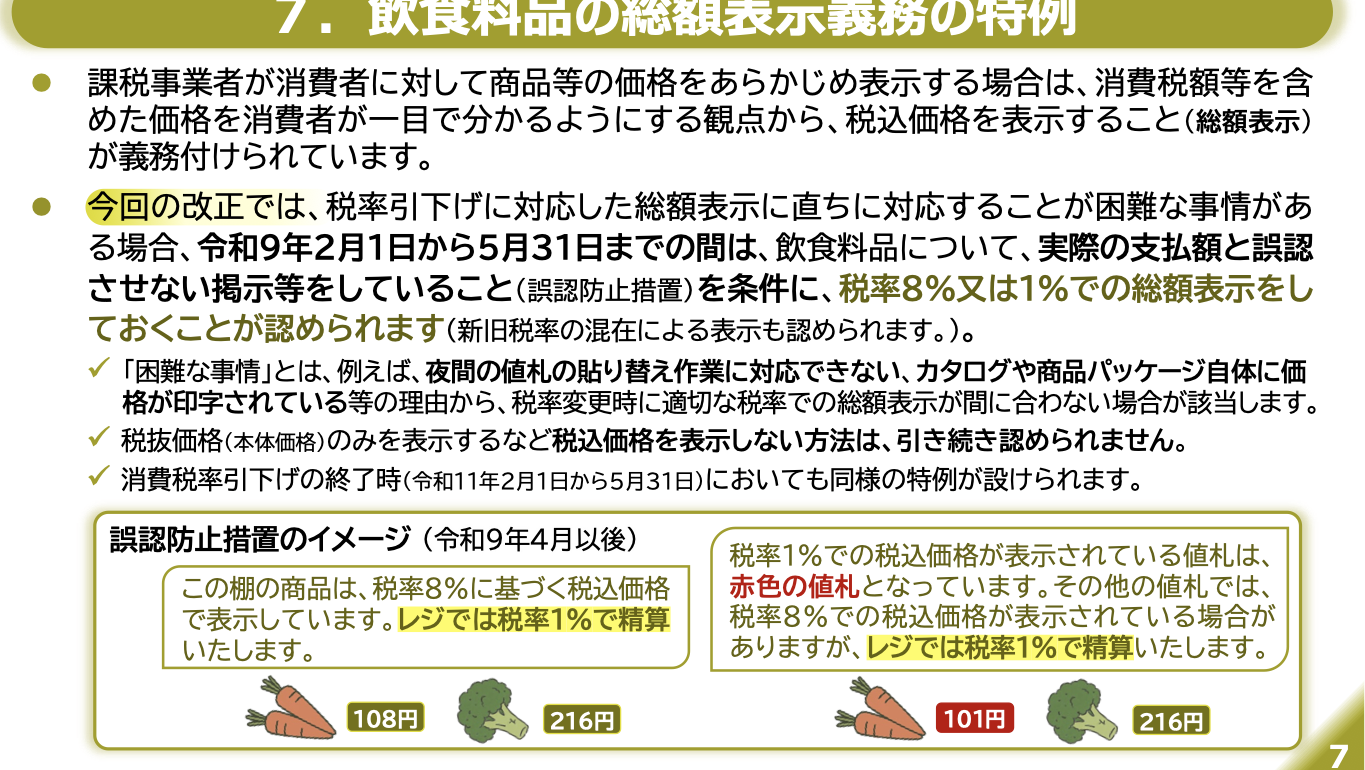
The details below all come from the same page of the pamphlet:
| Item | What the pamphlet says |
|---|---|
| Period | 1 February to 31 May 2027; the same special rule applies when the cut ends (1 February to 31 May 2029) |
| Examples of “difficulty” | A shop cannot replace price tags overnight; prices are already printed on a catalogue or on the packaging |
| Condition | A notice that prevents customers from being misled |
| Sample notice | “Items on this shelf are priced with 8% tax included. The till will charge 1%.” |
| Price tag colour | Tags showing the 1% tax-inclusive price are red; other tags may show the 8% tax-inclusive price, and the till will still charge 1% |
| Not allowed | Showing only the pre-tax price (the base price) without the tax-inclusive price |
| Official example | A food item at ¥100 before tax goes from ¥108 to ¥101 including tax |
So if a shelf price still looks old during those months, go by the amount charged at the till and look for the shop’s notice.
Transactions Around the Change: What Still Carries 8%
Pages 3 and 4 of the pamphlet say that for food delivered on or after 1 April 2027, two kinds of transaction still carry 8% (contracts made on the basis of 1% are excluded):
- A regular-supply contract signed before 1 January 2027, for the part already paid for before 1 April 2027, such as a prepaid subscription for monthly deliveries of seasonal ingredients.
- A mail-order sale where the terms were shown before 1 January 2027 and the order was accepted before 1 April 2027, such as a summer gift catalogue.
In addition, returns and bad debts on 8% sales that occur on or after 1 April 2027 are adjusted at 8%.
What Japan Consumption Tax at 1% Would Mean for Restaurants and Food Shops: The Special Rules to Look at First
This section is for people who run a restaurant, café or food shop in Japan. Everything here is the National Tax Agency’s description of rules that would apply only if the bill passes. For a specific return or application, check with a tax accountant (税理士) or the local tax office.
Food Retailers: With 1% Sales and 10% Purchases, a Refund May Be Possible
Page 4 of the pamphlet explains that consumption tax is calculated as tax on sales minus tax on purchases, and that a refund arises when the purchase side is larger. A food seller whose purchases and expenses carry 10% while its sales carry 1% may be able to receive a refund by filing under the general method. A tax-exempt business that wants a refund normally has to file a “Consumption Tax Taxable Business Election” form before the tax period starts. The bill’s special rule lets a tax-exempt food seller file it within the tax period that includes 1 April 2027, writing “飲食料品特例” (food special rule) in the reference column. For a sole proprietor, that would mean becoming a taxable business from 1 January 2027, with food sales from January to March taxed at 8%, and remaining taxable for both 2027 and 2028.
Businesses on the simplified tax system also get special rules. They may file a form withdrawing from the simplified system within the tax period that includes 1 April 2027 and switch to the general method for that period, and the usual requirement to stay on the simplified system for two years does not apply. For those who stay on the simplified system, the tax on purchases for food sales (1%) is counted as equal to the tax on those sales.
Restaurants and Businesses That Mostly Serve Dine-In: Purchases Fall to 1%, Sales Stay at 10%
If the tax on ingredients falls to 1% while dine-in sales stay at 10%, the tax that can be deducted on purchases shrinks. Here is an illustrative calculation, not an official example: with ¥1,000,000 of ingredient purchases before tax, deductible tax is ¥80,000 at 8% and ¥10,000 at 1%, which is ¥70,000 less, so the tax payable rises accordingly. The pamphlet also notes that restaurants whose purchases are taxed at 1% and sales at 10% will see their deductible purchase tax rise once the cut ends. It therefore provides special rules for interim returns: from 1 April 2027, an interim return may be based on a provisional recalculation that treats the previous period’s food sales and purchases as taxed at 1%, and after the cut ends, one that treats them as taxed at 8%.
Invoices and Tills
An invoice must show the applicable rate of 1% and the tax amount. Other required items stay the same, and there is no need to add wording such as “1% item”; the existing “reduced-rate item” mark can continue. The agency’s special website also links to a page for till and system developers with answers on tax questions.
Consumption tax is not only about food. For overseas owners of property in Japan, brokerage fees have carried 10% consumption tax since October 2026; Zagdim covers this in “Own Property in Japan From Overseas? Brokerage Fees Now Carry 10% Consumption Tax”.
Common Misunderstandings: Five Things People Get Wrong About Japan Consumption Tax
One: “Food is already at 1%”
Headlines often say that consumption tax is “going to 1%”, which can sound settled. In fact it is a bill submitted to the Diet on 9 October 2026, and every National Tax Agency explanatory document states that it applies only if the bill is enacted. When planning a trip, living costs or shop costs, use 8% and 10% today and treat 1% as a possible scenario.
Two: “Restaurants are all 10%”
Restaurant takeout is 8%. Only food eaten at the seats the restaurant provides is 10%. Being asked “eat in or take away?” at the till is normal, because the two carry different rates.
Three: “Alcohol will get cheaper too”
The bill’s scope matches the current 8% scope, which excludes alcohol, so alcohol stays at 10%. Alcohol-free beer and amazake (under 1% alcohol) are not alcohol under the law and count as food. A single receipt can therefore show beer and alcohol-free beer at different rates.
Four: “When the price tag changes, the till changes with it”
If the bill passes, shelves may still show the old 8% price from February to May 2027. Go by the amount charged at the till and by the shop’s notice.
Five: “The type of shop tells you the rate”
At one convenience store, a bento in the eat-in area and a bento taken away carry different rates; at one hotel, a soft drink from the in-room fridge and room service differ as well. What matters is how the food is provided. The National Tax Agency’s individual-cases Q&A is the most reliable guide.
Three Everyday Situations: An Office Worker, a Visitor and a Café Owner
An Office Worker in Tokyo: Lunch From a Convenience Store
Kobayashi (a pseudonym) works in Tokyo and often buys a bento at a nearby convenience store, sometimes taking it back to the desk and sometimes eating in the store’s eat-in area. Under the current rules, a bento taken away is 8% and one eaten in the eat-in area is 10%; telling the cashier at checkout is enough. If the bill passes, a takeaway bento would be 1% and an eat-in one still 10%, a much wider gap, but the amount actually paid is whatever the shop charges at the till.
A Visitor on a Few Weeks’ Stay: Supermarket, Izakaya and Alcohol
Emma (a pseudonym) is staying in Japan for a few weeks. She eats dinner in an izakaya and orders beer, and the next day buys fruit and alcohol-free beer at a supermarket. Under today’s rules, the izakaya meal and the beer are 10%, while the fruit and alcohol-free beer are 8%. If the bill passes, the fruit and alcohol-free beer would be 1%, while the izakaya meal and beer stay at 10%. Alcohol would not become cheaper because of this cut.
A Foreign Owner of a Small Café in Japan
Daniel (a pseudonym) runs a café with seating, serving both dine-in and takeaway. Today, dine-in is 10% and takeaway is 8%. If the bill passes, takeaway would be 1% and dine-in 10%. He would need to work out his monthly dine-in and takeaway mix and what share of purchases is ingredients, and discuss with a tax accountant whether the special filings in the pamphlet, and their deadlines, apply to him. Filing depends on individual circumstances, so confirm with a tax accountant or the tax office.
FAQ: Japan Consumption Tax Rates, Takeout, Alcohol and the 1% Food Bill
Is Japan consumption tax 8% or 10% right now?
Both rates exist. According to Tax Answer No. 6102, the standard rate is 10% (7.8% national consumption tax plus 2.2% local consumption tax) and the reduced rate is 8% (6.24% plus 1.76%). The 8% rate applies to food and drink other than alcohol, and to newspapers on regular subscription. Eating out and catering at your home are not eligible for 8%, and neither is alcohol. Different items in one shop visit can carry different rates.
Has the bill to cut Japan consumption tax on food to 1% passed?
No. The bill was submitted to the Diet on 9 October 2026, and the House of Councillors’ bill information page (as of 13 October 2026) shows every deliberation field still blank. NHK and Jiji Press reported on 16 October 2026 that the House of Representatives is scheduled to begin debate on 20 October and that the ruling side aims to pass it before the session ends on 12 December. The Diet vote decides the outcome.
If the bill passes, when would the 1% Japan consumption tax rate start and end?
According to the National Tax Agency, it would run from 1 April 2027 to 31 March 2029, two years, and apply only to sales of food and drink and to food and drink taken out of bonded areas. The agency’s pamphlet gives an example in which food sales from 1 April 2029 are again taxed at 8%. All of this depends on the bill being enacted.
How big is the tax gap between takeout and eating in at a convenience store?
Under the current rules, takeaway is 8% and eating in is 10%, a gap of 2 percentage points. If the bill passes, takeaway would be 1% and eating in 10%, a gap of 9 points. The rate is decided when the shop hands over the food, usually by the cashier confirming with you or through a notice in the shop, not by which bento you chose.
What are the rates on alcohol, alcohol-free beer and cooking sake?
Alcohol (1% alcohol by volume or more) is taxed at 10%, including beer, sake, wine and みりん. Alcohol-free beer and amazake (under 1% alcohol) are food and are taxed at 8% today, as are cooking sake that has had salt added so that it cannot be drunk, and みりん風調味料 (mirin-style seasoning). If the bill passes, those items would be taxed at 1%, and alcohol would not change.
What if the shop price tag has not been updated after the cut?
If the bill passes, from 1 February to 31 May 2027 shops may show food prices with either 8% or 1% tax included, provided they display a notice that prevents customers from being misled. A tag showing the 8% price still means the till charges 1%. Showing only the pre-tax price is not allowed. If you were charged the old price without any explanation, you can ask the shop to explain.
What happens if the Japan consumption tax bill does not pass?
The current 8% and 10% rules stay in place and are not changed by this bill. The National Tax Agency’s special website states that all of its tax-cut material assumes the bill is enacted. If the bill is amended during debate, the final period, scope or dates may differ from those published now, so follow the enacted text and the agency’s latest announcements.
Who can I ask about consumption tax if I run a business in Japan?
The National Tax Agency runs a consumption tax reduced-rate and invoice call centre on 0120-205-553 (toll-free within Japan, weekdays 9:00–17:00) for general questions. For a consultation that needs documents, you book through the tax office that has jurisdiction over you. A tax accountant can handle your own filing and applications for the special rules.
Still Have Questions? Ask Zagdim
If you live, travel or run a shop in Japan and want to work out how consumption tax affects your everyday spending, Ask Zagdim and describe your situation.
Life abroad? Ask Zagdim.
Your first stop for international property and global living.
Research and insights. Know what’s changing. Understand what matters.
Newsletter for overseas updatesSubscribe →
Important Disclaimer
This article is general information and does not constitute legal, tax or financial advice. It is based mainly on public material from Japan’s National Tax Agency, the House of Councillors and major media published between April and October 2026. The 1% food rate remains a bill awaiting debate in the Diet, and its provisions could be updated or amended. Readers should rely on the latest official announcements from Japan and, where needed, consult a qualified tax accountant.
Rules current as of 19 October 2026; the current 8% and 10% system is governed by the National Tax Agency’s latest announcements, and the 1% food rate by the outcome of the Diet’s deliberations.
References
National Tax Agency of Japan – Tax Answer No. 6102: The Reduced Consumption Tax Rate System / National Tax Agency of Japan – Q&A on the Reduced Consumption Tax Rate System (Individual Cases) / National Tax Agency of Japan and Ministry of Finance – Consumption Tax Rate Reduction Special Website / National Tax Agency of Japan – Two-Year Reduction of the Consumption Tax Rate on Food and Drink (Leaflet) / National Tax Agency of Japan – Two-Year Reduction of the Consumption Tax Rate on Food and Drink (Pamphlet) / House of Councillors – 222nd Diet Session Bill Information (Bill on a Temporary Reduction of the Consumption Tax Rate on Food and Drink) / NHK – Bill Cutting the Consumption Tax Rate on Food to 1% for Two Years From Next April Approved by Cabinet (9 October 2026) / NHK – Consumption Tax Cut Bill to Enter Debate in the House of Representatives on the 20th (16 October 2026) / Jiji Press – Consumption Tax Cut Bill to Begin Debate on the 20th (16 October 2026) / Kyodo News – Tax Cut Bill to Begin Debate on the 20th (16 October 2026) / Kyodo News – Cabinet Approves Bill for 1% Consumption Tax on Food (9 October 2026) / Zagdim – Own Property in Japan From Overseas? Brokerage Fees Now Carry 10% Consumption Tax






