Holding costs are the ongoing expenses an owner faces for as long as they hold title to a German property. Different activities generate different costs: letting a unit generates income tax, and an overseas owner will typically also pay for a property management service. This article covers the required running costs of owning German property, and the additional costs that apply depending on the owner’s situation.
Property Tax (Grundsteuer)
Property tax is a German municipal tax, levied by the city or municipality where the property is located. It is established under Germany’s Property Tax Act (Grundsteuergesetz, GrStG), and is one of German local government’s most important sources of revenue. The local tax authority (Finanzamt) determines the amount for each district, and the municipality collects it as of January 1 each year. It is payable whether or not the property is rented out, though an owner can apply for an exemption in the case of unforeseen events such as fire or flood damage. A landlord can pass property tax on to the tenant through rent. Separately, letting below market rent affects income tax, not property tax: under §21(2) EStG, letting at less than 50% of the local market rent means related expenses can only be deducted proportionally, while letting at 66% or more of market rent allows the full expense deduction.
Since Germany’s 2025 property tax reform (Grundsteuerreform), the federal-model tax rate factor (Steuermesszahl) for residential property is a uniform 0.31 per mille, applied to a newly assessed property tax value (Grundsteuerwert, valuation date 1 January 2022) — not the older 0.26%-1% figure based on the previous valuation system. Some states (e.g. Bavaria, Baden-Württemberg, Hamburg, Hesse, Lower Saxony) use their own state model with a different calculation.
Property tax is paid quarterly, on February 15, May 15, August 15, and November 15 each year, to the local tax office. Where the total due does not exceed €15, it must be paid in full by August 15. Where it does not exceed €30, it can instead be split into two payments, due February 15 and August 15.
Building and Service Charges
Building-related costs generally fall into three categories: day-to-day utility-type charges — garbage collection, electricity, water, sewage, and snow-clearing fees — which, where a lease specifies “warm rent,” are paid by the tenant; a building maintenance reserve fund, contributed to monthly by all the building’s owners together and drawn on when common areas need repair; and the property management company’s own fee for managing the building. A detached house does not carry a management fee or maintenance reserve fund in the same way, but day-to-day utility costs — sewage, water, electricity, heating — still apply. Costs of this kind are unavoidable for anyone holding German property.
Other costs — gas, water, wastewater, elevator, TV, internet, building cleaning, gardening, and concierge fees — are also borne by the tenant, either prepaid together with the rent or paid directly to the relevant organizations. In practice, a property manager will usually collect these advance payments and handle billing on the owner’s behalf, including issuing the tenant an annual settlement statement.
If an owner occupies the property themselves rather than letting it, they must pay these costs directly. In Germany these are known as “operating expenses,” and can be estimated at roughly €1.70-2.50 per square meter per month, covering all running costs together — the exact figure depends on how much the owner actually uses.
Remittance Fees
Paying these various costs involves using a bank, whether the owner is based in Germany or overseas, so remittance fees apply. The cost is more pronounced for an overseas owner, since payments may involve international transfers.
Rental Income Tax
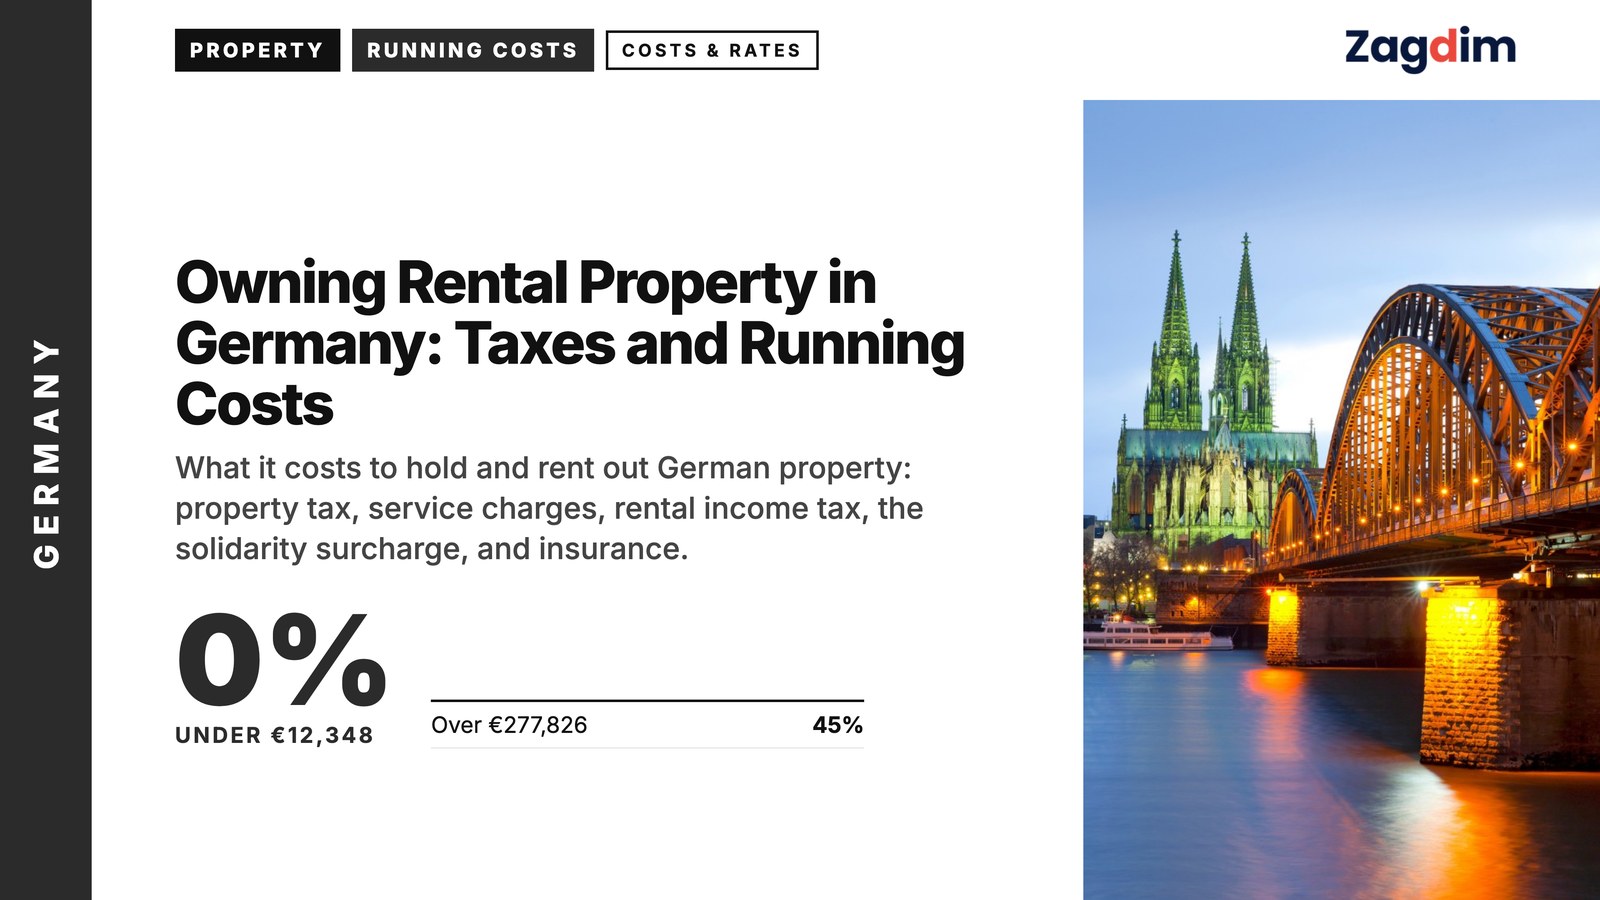
If net rental income from a German property exceeds the basic tax-free allowance, the owner must pay income tax on it. This applies regardless of whether the owner is a German resident: any income generated within Germany is taxable, so an overseas owner holding German property must also declare and pay tax on rental income. The tax is calculated on net rental income — meaning deductible costs, such as running costs and management fees, are subtracted first — on a progressive scale. For the 2026 tax year:
| Taxable Income | Tax Rate |
|---|---|
| Under €12,348 | 0% |
| €12,349 – €69,878 | ≈14%-42% |
| €69,879 – €277,825 | 42% |
| Over €277,826 | 45% |
These thresholds are adjusted for inflation most years — check the current figures before you rely on them.
Deductible Expenses
An owner of a non-owner-occupied German property can deduct rental-related expenses when calculating income tax, provided the reason is a reasonable and logical one — for example, mortgage interest on a buy-to-let loan, the building’s management fees, and depreciation on the property’s value. Advertising costs incurred to find tenants, and legal or agent fees related to letting, can also count as valid deductions.
Depreciation
Depreciation applies to interior and exterior fixtures and fittings rather than the land itself, and is calculated from the date of purchase rather than the building’s year of construction. For example, a kitchen, or any single piece of furniture costing more than €1,000, can be depreciated over 10 years, at 10% a year. As a general rule, the depreciation and other deductible costs available tend to be lower on a new building and higher on an older, existing one.
Germany’s income tax calculator can be used to work out the applicable rate.
Solidarity Surcharge (Solidaritätszuschlag)
The solidarity surcharge (Solidaritätszuschlag / “Soli”) is a 5.5% surcharge on income tax, capital gains, and corporate tax, introduced in 1991 to help fund German reunification. Since a 2021 reform, individual income-tax payers owe no Soli at all if their income-tax liability is below roughly €20,350 (single) / €40,700 (joint) — around 90% of income-tax payers are now fully exempt. Capital-gains withholding tax and corporate tax generally still carry the full 5.5% surcharge with no such exemption. When East and West Germany merged, the surcharge was added to (originally) West German residents’ income to help balance development between the two and support the former East Germany’s development; today, it is collected across the whole of Germany.
Property Management Fees
Because Germany is a large country with many major cities, many owners hold property in a different city from where they live, which makes self-management impractical — hence the property management company, engaged by the owner to handle the day-to-day business of letting. This is unavoidable in particular for an overseas owner. Property management fees are generally charged based on whether the unit is currently let, at roughly €15-30 a month, varying according to the property’s location, size, and use.
Insurance
German property owners can choose from three types of insurance: building insurance, household/contents insurance, and third-party liability insurance. Current law does not require any of these, though most rental agreements will require the landlord to hold household/contents insurance. As an example, household insurance costs around €50-60 a year and can provide roughly €200,000 of coverage, making it a useful way for an owner to manage risk. Separately, where a property is mortgaged, the lender will typically require fire and flood insurance. Public liability insurance is also common, covering incidents such as an accident caused by snow left uncleared outside the property.
Summary
These are the main costs of holding property in Germany, though not every cost applies to every owner — it is worth checking with a local agent or lawyer about your specific situation before buying, or reviewing the property’s land register entry, to get a more accurate picture. On the whole, the tax burden of holding German property is not heavy: mainly a modest annual property tax, plus income tax on any rental income. The income tax rate can look high on paper, but many necessary expenses are deductible, so it is worth consulting a local tax advisor or accountant before filing, to avoid overpaying and affecting your return.
Have a question about this guide? Leave a comment below, or ask Zagdim directly.
Your first stop for international property and global living.
Research and insights. Know what’s changing. Understand what matters.